Showing posts with label online stock market trading. Show all posts

Weekly Market Outlook - SNAPSHOT - By Mansukh - 23July 2011

SNAPSHOT

Indian equity markets, which failed to extend the winning momentum last week, resumed the northward journey by settling with close to a percent gains in the week ended July 22. The enthralling week saw the frontline indices being buttressed not only by encouraging reports from the domestic front but also by easing concerns over global financial stability. The Bombay Stock Exchange (BSE) Sensex gained 160.38 points or 0.86% to 18722.30 during the week ended July 22, 2011. The BSE Mid-cap index was up by 39.37 points or 0.56% to 7046.12 and the Small-cap index was up by 100.27 points or 1.20% to 8463.49.  The S&P CNX Nifty gained 52.85 points or 0.95% to 5633.95. On the National Stock Exchange(NSE), Bank Nifty increased by 57.40 points or 0.51% to 11291.95, CNX IT surged 92.45 points or 1.46% to 6438.50 while CNX mid-cap lost 21.30 points or 0.26% to 8153.90 and CNX Nifty Junior slipped 111.70 points or 0.98% to 11278.45. India's food inflation has once again resumed its declining trajectory as the Food Articles group rose 7.58% in the week ended July 9 compared to 8.31% in the previous week. The Empowered Group of Minister (EGoM) on food headed by Finance Minister Pranab Mukherjee removed the four year ban from export export of wheat.

Meanwhile, Indian agriculture production registered a record increase of around 11% during the 2010-11 agriculture season while ministry of finance approved 31 foreign direct investment (FDI) proposals worth Rs 3844.70 core. The domestic indices were largely influenced by the encouraging developments from the Euro-zone where European Union leaders carved out a second bailout package worth 109 billion euros ($157 billion) for debt-stricken Greece in a desperate effort to contain the 18 month long debt crisis in Europe, which is threatening to spread to much larger economies.

Weekly Market Outlook - SNAPSHOT - By Mansukh - 16July 2011

SNAPSHOT

Indian benchmark indices failed to extend the winning run for the fourth straight week and halted the weekly uptrend with around one and half a percent losses. The eventful week saw the frontline indices being tormented not only because of domestic reasons but also by worsening global financial situation. The markets got off to a subdued opening for the week as last Friday's pessimism got spilled into Monday's session. What unfolded in the next couple of days was a nasty cut of over one and half a percent followed by a recuperation of around a percentage points. The bourses were destined for similar fortune in the next two days as well but the magnitude of gains and losses was moderate. Then came the extremely disappointing IIP numbers for the month of May which unexpectedly slowed to 5.6% from a year earlier, confirming the signs that the economy is losing steam after a string of interest rate hikes by RBI. Meanwhile, monthly WPI inflation numbers released by the government gave some respite to the markets as it increased to 9.44% in June against 9.06% in the previous month, whereas economists had forecast a gloomier picture and a sharper rise to 9.7% because of the recent hike in prices of petroleum products by the government.
However, the relief proved temporary as weak monsoon data took its toll on sentiments. The Bombay Stock Exchange (BSE) Sensex lost 296.12 points or 1.57% to 18561.92 during the week ended July 15, 2011. The BSE Mid- cap index gained marginally by 10.44 points or 0.15% to 7006.75 and the Small-cap index lost 11.92 points or 0.14% to 8363.22. The S&P CNX Nifty declined by 79.55 points or 1.41% to 5581.10. On the National Stock Exchange (NSE), Bank Nifty lost 50.60 points or 0.45% to 11234.55, CNX IT slipped 377.80 points or 5.62% to 6346.05 while CNX mid- cap increased by 59.30 points or 0.73% to 8175.20 and CNX Nifty Junior gained 33.40 points or 0.29% to 11390.15.

Weekly Market Outlook - SNAPSHOT - By Mansukh - 2nd July 2011


SNAPSHOT

Boisterous Indian benchmarks witnessed an awe-inspiring week of trade as they carried forward their exhilaration from the previous week and vivaciously rallied over 1,250 (Sensex) and 350 (Nifty) points from last Thursday to this Thursday. However, the frontline indices receded on Friday, halting a six-day advance, as some investors judged the recent rally as excessive and resorted to profit booking on speculations that fundamentally things have not changed much and also on expectations that Reserve Bank of India would continue its tightening measures until there are clear signs of inflation easing. Nevertheless, the frontline indices accumulated around three percent points for the week, the largest weekly gain since late March as optimistic global cues coupled with encouraging local developments fortified investors' mood. Foreign institutional investors showed renewed vigor in Indian equities following the government's decision to hike prices of petroleum products while the reduction in customs and excise duty came as an incremental positive surprise for them. The net FII inflow in the equity stood at over Rs 4,600 crore till Thursday.


The core infrastructure industries registered a slowdown in the pace of growth in the month of May, coming down at 5.3% compared to 7.4% registered in May 2010, mainly due to increased interest rates and confusion on policies. The RBI has raised interest rates 10 times since March 2010 to tame inflationary pressures and has made its intention clear to sacrifice some growth to calm inflation. The food inflation numbers showed signs of cooling in the week ended June 18, According to the data released by Ministry of Commerce and Industry, the index for Food Articles group rose to 7.78% for the week-ended June 18, from 9.13% for the previous week.

Learn How To Start Investment in Stock Market?

HOW TO START?

1) In order to buy / sell a share, you need to first become a client of one of the stock market members who are commonly known as stock brokers.
2) Open Demat A/c
3) Open Trading A/c

MARKET MECHANISM

1) A stock market has many members who co ordinate for various activities in the process of placing orders, their execution and settlement etc. A person who desires to buy / sell shares in the stock market, can place his order through the broker either in the traditional manner or can place an online order himself through the terminal provided by the broker.

2) Two trading days are considered for settlement where Saturday, Sunday, Bank Holidays and trading holidays are not considered as working days for settlement. Hence, a trade done on Monday will get settled on Wednesday.

DO AND DON'TS

1) Always consult a professional. In order to avoid any mistakes in your investment decisions, you should always consult a professional to plan out your investments and to get qualified investment advice.

2) Keep yourself updated with latest market news If you are investing in equity, it is advised that you keep yourself updated about the latest market news as there are a lot of announcements that take place from day to day such as mergers, acquisition, dividends, Annual Meetings etc. This helps you to get a clue as to what is the effect of such news on your investments and what is the expected return from your investment.

3) Don't put blind faith in a stock tip from unofficial sources it is important to do some homework on the investment that you are planning to make. Don't just believe everything that is said about any stock tip from your friends or near n dear ones. If you come across any such tips, you should first verify it for its authenticity and then take your investment decision.

4) Don't put all your money in one sector or stock In equity investment, there are shares available for companies that cover almost every sector of the commercial sphere and thus provide you the opportunity to invest into a wide variety of sectors. Every sector or stock is affected by some or the other factors of the economy and as a result of it affect your investment in these stocks / sector.

About Author: MANSUKH investment & Trading services is an Online Trading Solution provider giving you ideas about latest stock market happenings, Online Share Trading, investment services, mutual funds and other offerings with advice to both fledgling investors and experienced day traders. For Best Stock Market updates visit their site http://moneysukh.com 


Always consult a stock market broker. In order to avoid any mistakes in your investment decisions, you should always consult a professional to plan out your investments and to get qualified investment advice.

Stock Market Tutorials for Beginners

WHAT IS STOCK MARKET?

Different business in India are having their expansion plans, all together they can't manage to have such big amount to use, so they are calling people to participate in their companies and get profit out of that in form of dividend, stock split, bonus share etc. Most stocks are traded on exchanges, which are places where buyers and sellers meet and decide on a price. Some exchanges are physical locations where transactions are carried out on a trading floor. The purpose of a stock market is to facilitate the exchange of securities between buyers and sellers, reducing the risks of investing.


WHY COMPANIES ISSUE STOCK?

1. When a company would like to grow, it issues stocks to raise funds and pay for ongoing business activities.
2. It is popular because:
I. The company does not have to repay the money
II. Paying dividends is optional
* Dividends are distributions of earnings paid to stockholders


STOCK MARKET BASICS

1. A stock is a tradable security that a firm issues to certify that the stockholder owns a share of the firm.
2. A share represents an investor's ownership in a "share" of the profits, losses, and assets of a company. It is created when a business carves itself into pieces and sells them to investors in exchange for cash.
3. In order to buy / sell a share, you need to first become a client of one of the stock market members who are commonly known as stock brokers.


STOCK EXCHANGE IN INDIA
1. The Bombay Stock Exchange (BSE)
2. National Stock Exchange of India Ltd (NSE)

FACTORS AFFECTING STOCK MARKET
1. Inflation
2. GDP
3. Global Markets
4. Govt policies
5. Market trends
6. Financial statements
7. News

FACTORS AFFECTING STOCK PRICE
1. Financial statement
2. Order book
3. Management
4. Land bank
5. Future plans
6. Growth
7. Commodity prices


About Author: MANSUKH investment & Trading services is an Online Trading Solution provider giving you ideas about latest stock market happenings, Online Share Trading, investment services, mutual funds and other offerings with advice to both fledgling investors and experienced day traders. For Best Online Commodity Services visit their site http://moneysukh.com

Weekly Market Outlook 25th June 2011

SNAPSHOT
Indian stocks markets finally succeeded in salvaging a close in the positive territory, snapping the two week downtrend, as the enthralling close to 700 points rally in the last two trading session of the week for the Sensex helped it to overturn the massive losses incurred on the initial day of the week. The benchmark indices went on to re-capture the important psychological 5,450 and 18,200 levels and end the week with close to two percent gains amid encouraging global cues including a resolution over Greece debt trouble after it gained EU and IMF's approval of its latest five-year austerity plan and also after a decision by International Energy Agency to increase oil supplies. However, what followed in the last two sessions was healthy short covering rally as it seemed like investors keenly awaited for a catalyst to buy in India since they were of the belief that domestic markets have bottomed out and a lot of headwinds have been factored in. The BSE Sensex surged by 370.15 points or 2.07% to 18240.68 during the week ended June 24, 2011. The S&P CNX Nifty heaved by 104.85 points or 1.95% to 5471.25.

Food inflation numbers have ricocheted a week after showing some signs of moderation. According to the data released by Ministry of Commerce and Industry, the index for Food Articles group rose to 9.13 percent for the week-ended June 11, from 8.96 percent for the previous week. The Consumer Price Index (CPI) stood at 107 points in May 2011, higher by 7% as compared to the base of 100 in 2010 and marginally up by 0.1% from the month of April. Foreign Institutional Investors (FIIs) were net sellers in the equity segment in the week with gross purchases of Rs 10400.60 crore and gross sales of 11526.70 crore, leading to a net outflow of Rs 1126.10 crore.


Weekly Market Outlook 18th June 2011

 SNAPSHOT

Indian equity indices extended the downtrend for the second consecutive week as investors at large continued to avoid long positions amid an increasingly vulnerable global as well as domestic setup. The hefty position squaring in last three session of the week proved very costly for the benchmark indices as it plunged over two percent on week on week basis. Foreign institutional investors (FII) restlessly attempted to plough back their hot money from the domestic markets because of confluence of worrying economic trends like accelerating inflation, declining foreign investment and slower growth and domestic investment, that policy inertia is only making worse. The BSE Sensex lost 398.01 points or 2.18% to 17870.53 during the week ended June 17, 2011. The BSE Mid-cap index plunged by 83.49 points or 1.21% to 6814.79 and the Small-cap index declined by 113.97 points or 1.38% to 8174.49.The S&P CNX Nifty slipped by 119.40 points or 2.18% to 5366.40. On the NSE, Bank Nifty lost 116.00 points or 1.08% to 10598.25, CNX IT sank 296.35 points or 4.45% to 6357.10 while CNX mid-cap declined 70.90 points or
0.89% to 7921.15 and CNX Nifty Junior dropped 227.20 points or 2.01% to 11051.25.

The annual rate of inflation, based on monthly WPI, came much higher than the expectation at 9.06% (Provisional) for the month of May, 2011 (over May, 2010) as compared to 8.66% (Provisional) for the previous month and 10.48% during the corresponding month of the previous year. RBI furthered its aggressive stance against the rampant inflation and hiked repo rate and reverse repo rate by 25 basis points each to 7.50% and 6.50% respectively, in its mid-quarter policy review, which was in line with broader market expectations. 


Read More: Equity Research Weekly Report


Weekly Market Outlook 4th June 2011


SNAPSHOT

Despite concluding three out of the five trading session of the week in the negative zone, Indian benchmarks still negotiated a close in the green territory with gains of well over half a percent on the week on week basis. In their journey, the key indices also went on to break the two week downtrend but failed to hold on to the psychological 5,600 and 18,650 levels. Investors went through a hectic week as an assortment of reports popped through the period keeping investors in a dilemma and frontline indices in a sticky situation. Bullishness seemed to be returning to the markets which were evident from the fact that the frontline indices showed some resilience and did not capitulate despite an assortment of disappointing economic reports. To start with it was the GDP data released on Tuesday which showed that nation's economy grew by 7.8% in the fourth quarter ending March this year, mainly due to poor performance of the manufacturing sector. On Wednesday, the HSBC PMI figures based on a survey of around 500 companies were released which showed manufacturing activity in India in May slowed from a month earlier, yet output remained robust, reflecting the underlying strength in business conditions.

Furthermore an official data released by the Ministry of Commerce showed that India's six core industries grew by 5.2% in April 2011 as compared to 7.4% in the previous month and 7.5% in the same month of last year. Another data released by the commerce ministry showed that India's trade deficit in April narrowed to $8.98 billion from $11.03 billion in the same period a year earlier, however, the trade deficit rose (month on month) to $8.98 billion in April from $5.6 billion in March.

Read More: Equity Research Weekly Report

Derivative Strategy On Futures And Options - Mansukh 2nd-May-2011

Derivative Strategy Report
F & O HIGHLIGHTS

Future & Option (F&O) total turnover stood at Rs 101034.98 crore on April 29, and the total numbers of contracts traded on the day were 3555026.
Of the total turnover, Index Futures contributed Rs 13211.83 crore, Stock Futures Rs 13710.62 crore, and Index Options Rs 71458.45 crore while the contribution of the Stock Options was of Rs 2654.08 crore.
For the day the total F&O PutCall ratio stood at 0.94 while Index Options PutCall ratio was 0.97 and that of Stock Options was 0.38
The top five scrips with highest PCR on OI were Siemens 2.89, Mpasis 1.33, Reliance Infrastructure 1.24, HCL Tech1.11 and Bank of India 1.
Among most active underlyings ICICI Bank witnessed an addition of 4.06% in the May month futures contract, followed by Reliance which saw an addition of 3.58% of OI in the near month contract. SBI witnessed an addition of 5.81% in the next-month futures; followed by Infosys witnessed an addition of 8.05% in the May month futures contract and L&T witnessed an addition of 13.64% in the May month futures contract.

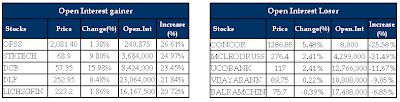
Open Interest Gainer & Looser

Nifty Open Interest
Nifty Option Open Interest Distribution
Nifty May 5800 call added 18.07 lakh shares in OI, up 89.79% and 5900 call added 8.91 lakh shares in OI, up 37.02%. On the put side nifty May 5700 put added 10.76 lakh shares in OI, up 30.33% and 5600 put added 9.61 lakh in OI, up 24.99%. The put-call ratio of stock option decreased from 0.42 to 0.38 while put-call ratio of index option increased from 0.79 to 0.97. On the whole the put call ratio was at 0.94.

Read more about Derivative Strategy Report

Related post about Derivative Strategy On Futures And Options Report by Mansukh

Equity Research Weekly Market Outlook Report By Mansukh 17-April-2011

Weekly Markets, Net  FII / DII Equity Activity (Rs Cr)
SNAPSHOT
For the week ended 15 April 2011, the BSE-Sensex declined by 64.63 points or 0.33% to 19,386.82. The BSE Mid-cap index increased 35.67 points or 0.50% to 7209.17 and the Small-cap index advanced 35.61 points or 0.41% to 8,808.16.On the sectoral front, FMCG zoomed 76.31 points or 2.10% to 3,713.73, Capital Goods (CG) soared 237.52 points or 1.73% to 13,979.29, Bankex surged 83.79 points or 2.80% to 13,382.96, Auto jumped 41.95 points or 0.45% to 9,439.08 and Healthcare (HC) up by 18.53 points or 0.31% to 6,142.02, were the top gainers on the BSE. On the flip side, IT was down by 299.41 points or 4.57% to 6,258.54, TECk was down by 119.75 points, or 3.09% to 3,751.26, Realty was down by 54 points or 2.19% to 2,410.15, Metal was down by 125.88 points or 0.76% to 16,381.24 and Consumer Durables (CD) down by 45.86 points or 0.71% to 6,381.24 were the top loser on the index. The S&P CNX Nifty lost 17.45 points or 0.30% to 5,825. On the National Stock Exchange (NSE), CNX IT tumbled 4.56% to 6,842.15 while CNX mid-cap gained 0.36% to 8,317.85, Bank Nifty gained 0.53% to 11,735.65 and CNX Nifty Junior advanced 0.54% to 11606.20.
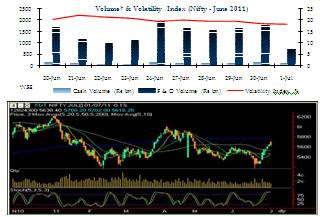
Volume & Volatility Index(Nifty- April 2011)
WEEK GONE BY
After minutely escaping from dipping into the red terrain in the previous week, the frontline indices slipped into the negative territory this time around, though marginally, as the triple 'I's viz. IIP numbers which merely grew at a pace of 3.6%, Inflation stood at 8.98% in March against 8.31% in Feb 2011 and Interest Rates, continued to haunt the domestic benchmarks for quite some time now, quadrupled with Infosys being the latest addition to the list. The psychological 5,800 and 19,400 levels proved to be a strong supports for the BSE' Sensex and the NSE Nifty as they consolidated around these levels for yet another week and looked in no mood to give away the substantial gains accumulated two weeks ago. The over 3% laceration in international crude oil prices which were trading around two and half year high levels, on the back of apprehensions of sluggish demand and slow economic recovery, too eased investor concerns. However the bourses, after another one-day break, took a nasty blow of around one and half a percent on the back of dreadful local leads. The flavor of a hectic earning season turned bitter right from the very start and the frontline indices took a blow after IT bellwether Infosys reported below expectation quarterly earnings and gave even lower than expected EPS guidance for FY12.

WEEK AHEAD
After having an imperative numbers of economic data last week the next big aspect that will be driving the Indian equity markets will be other corporate quarterly reports as earnings season shifts into high gear in the coming week. Companies like HDFC Bank, IFCI, IndusInd Bank, Magma Fincorp and Persistent Systems will be reporting their numbers in the week. Since there will be no major economic data up for release in the coming week the investor's will continue to watch the crude oil prices and Foreign fund inflows for cues since these two factors have been dictating the market's movements from quite some time now. Meanwhile, the Government of India in the coming week will take up 46 foreign investment (FDI) proposals. From the global markets investors will be eying lots of major economic data from the US, starting with Housing Starts data on April 19, followed by Existing Home Sales, Jobless Claims and finally the Philadelphia Fed Survey data on Thursday, April 21, 2011. For the coming week 5720 followed by 5605 are likely to be good support levels for the Nifty, while the index may face some resistance at 5950 and 6070 levels.HAPPY TRADING….

Read more about Weekly Market Outlook
Related post about Equity Research Report by Mansukh 

Derivative Strategy On Future And Options Daily Report By Mansukh 15th-April-2011

Derivative Commodity
F & O HIGHLIGHTS
Nifty April 2011 futures closed at 5,798.00, at a premium of 12.30 over spot closing of 5,785.70, while Nifty May 2011 futures were at 5,816.00 at a premium of 30.30 points over spot closing. The near month April 2011 derivatives contract expires on Thursday, April 28, 2011. Nifty April futures saw an addition of 10.22% or 2.60 million (mn) units, taking the total outstanding open interest (OI) to 28.04 mn units.
From the most active underlying, SBI's April 2011 futures closed at a discount of 3.40 points at 2779.25 compared with spot closing of 2782.65. The number of contracts traded was 14,880.
ICICI Bank April 2011 futures were at a premium of 3.70 points at 1101.70 compared with spot closing of 1098.00. The number of contracts traded was 13,462.
Tata Motors April 2011 futures were at a discount of 3.50 points at 1213.50 compared with spot closing of 1217.00. The number of contracts traded was 11,935.
Infosys April 2011 futures were at a premium of 10.80 points at 3247.65 compared with spot closing of 3236.85. The number of contracts traded was 8,359.
Derivative Research Report

Read more about Derivative Research Report By Mansukh
Related  Post Derivative Trading

Equity Research Weekily Report by Mansukh (7-March-2011)

Equity research report
SNAPSHOT
With an exception of the last trading day of the week, Indian benchmarks showed high-spirited performance in four back to back sessions of the passing week as they extended last Friday's pullback rally with bottom fishing in fundamentally strong shares gathering greater force. Markets finally witnessed the much needed relief as they commenced the week with around 500 points rally,though took a couple of days off to consolidate and then made another move upto 5,500 on Thursday. However, all the good work was partly undone by Friday's trade as the frontline indices capitulated to the selling pressure exerted by bears of the market. Meanwhile India VIX, a gauge for market's short term expectation of volatility, gained 7.13% at 24.18 from its previous close of 22.57 on Thursday (Provisional).


WEEK GONE BY
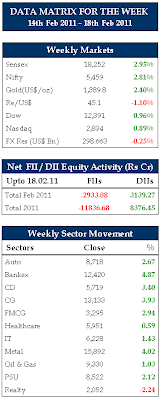
The Bombay Stock Exchange (BSE) Sensex surged by 482.91 points or 2.72% to 18211.52 during the week ended February 18, 2011 while the S&P CNX Nifty was up by 148.95 points or 2.81% to 5458.95. The BSE Mid-cap index was up by 2.87% to 6661.65 and the Small-cap index zoomed by 4.10% to 8128.91. On the National Stock Exchange (NSE), CNX Nifty Junior dipped 3.00% to 10406.25, CNX IT tumbled 1.91% to 6719.65 and CNX midcap was the worst performer, declining by 3.45% to 7483.9. On the other hand Bank Nifty closed flat, up by 0.13% to 10447.75. In the BSE sectoral space, there was only one loser, Realty down by 2.24% for the week to snap the week at 2052.11. On the other hand, Bankex was the biggest gainer up by 4.87% to 12419.72, followed by Metal up by 4.02% to 15892.31, Capital Goods (CG) up by 3.93% to 13132.51, Consumer Durables (CD) up by 3.40% to 5719.04, Fast Moving Consumer Goods (FMCG) up by 2.94% to 3295.36, Auto up by 2.67% to 8717.71, Public Sector Undertakings (PSU) up by 2.12% to 8522.38, Power up by 2.09% to 2611.98 and TECk up by 1.53% to 3647.97.