Showing posts with label Broking House India. Show all posts

Equity Research Weekly Market Outlook Report By Mansukh 14th May 2011

Weekly Market
SNAPSHOT
Volume & Volitility IndexIndian benchmarks have gone through every possible circumstance in the passing week, to start with it was consolidation which prolonged for three back to back sessions, thereafter followed a day of turmoil for the frontline indices only to sign off the week with an enthusiastic short covering rally. Markets seem to have formed a firm base around the psychological 5,550 and 18,500 levels and are showing little signs of budging from those levels despite the amount of volatility seen in the markets. Investors at large remained hesitant to build on positions ahead of a slew of announcements like IIP data, weekly inflation figures, export data and the outcome of assembly polls. The initial three sessions remained characterized by volatility as traders utilized every small rise to trim down their positions and book profits. Nevertheless, despite the late correction, the frontline indices managed to accumulate around a percent gains in the session as domestic investors cheered the ruling UPA's win against the Left Parties in West Bengal, Kerala and Assam which may strengthen the image of the beleaguered government.

WEEK GONE BY
The Bombay Stock Exchange (BSE) Sensex remained flat gaining 12.47 points or 0.07% to 18,531.28 for the week ended May 13, 2011. The BSE Mid-cap index shed 19.62 points or 0.29% to 6844.16 and the Small-cap index declined 7.15 points or 0.09% to 8,335.43. On the sectoral front, Capital goods lost 81.26 points or 0.64% to 12688.62, Bankex shed 80.59 points or 0.64% to 12590.17, Oil Gas declined by 46.36 points or 0.47% to 9768.78, IT lost 17.17 points or 0.28% to 6039.60 and Consumer Durables trimming 4.46 points or 0.07% to 3210.24, were the top losers on the BSE while FMCG up by 160.72 points or 4.41% to 3803.26, Realty advancing 82.58 points to 3.94% , Health Care (HC) surging 85.20 points or 1.40% to 6149.40, TECk climbing 18.21 points or 0.50% to 3629.23 and Metal rising 41.02 points or 0.27% to 15404.23 were the main gainers on the sectoral space. The S&P CNX Nifty lost 6.70 points or 0.12% to 5544.75. On the NSE, Bank Nifty lost 1.11% to 11020.95, CNX IT tumbled 0.26% to 6609.55 while CNX mid- cap gained 0.87% to 8034.90 and CNX Nifty Junior surged by 1.74% to 11,185.40. India's food inflation numbers have managed to extend the downtrend for second straight week and have moderated sharply to 7.70% for the week ended April 30 from 8.53% seen in the previous week. India's industrial growth-IIP has surprisingly jumped to 7.3% in March from 3.6% in February; however the Industrial production had grown 15.5% a year ago.

WEEK AHEAD

With the prices of crude oil and FII movements being the constant decisive factors for the markets, the investors in the coming week would be watching the Wholesale Price Index (WPI) data for the month of April for cues. As per the street expectation that India's wholesale price index likely rose 8.43 percent in April from a year earlier, slower than March's 8.98 percent increase due to base effect. Moreover, the postponed meeting of Empowered Group of Ministers (EGoM) for a decision on increasing the prices of diesel and domestic LPG will be taken only by May 17 or 18. Earlier EGoM was to meet on May 11, 2011 to consider hiking the diesel price by Rs 3-4 a litre and domestic LPG rates by Rs 20-25 a cylinder. Moreover trend line drawn adjoining two significant bottoms 5177 and 5232 , next level of support could be around 5430 level where possibility of bounce back couldn't be rule out. Hence clients are advised to remain cautious and use 'Buy on Dip' strategy on any substantial correction. On the flip side 5760-5770 (200 DMA) could be the key resistance zone where we might see some selling pressures. Any closing above this level with substantial volumes may boost the traders sentiment however 5945-5960 could be the next resistance zone. HAPPY TRADING......

Read more about Weekly Market Outlook Report By Mansukh

Nifty Apr Fut closed at a premium of 25.55 points ! Derivative Report By Mansukh 29th-april-2011

Derivative Research Report
F & O HIGHLIGHTS
Nifty April 2011 futures closed at 5,785.20, at a discount of 0.25 points over spot closing of 5,785.45, while Nifty May 2011 futures were at 5,811.00 at a premium of 25.55 points over spot closing. The near month April 2011 derivatives contract expires today. Nifty April futures saw contradiction of 3.93% or 0.52 million (mn) units, taking the total outstanding open interest (OI) to 12.83 mn units.
From the most active underlying, ICICI Bank April 2011 futures closed at a premium of 5.25 points at 1117.40 compared with spot closing of 1112.15. The number of contracts traded was 41,387.
ICICI Bank May 2011 futures were at a premium of 8.45 point at 1120.60 compared with spot closing of 1112.15. The number of contracts traded was 39,310.
SBI's April 2011 futures were at a premium of 7.00 points at 2855.35 compared with spot closing of 2848.35. The number of contracts traded was 20,979.
Infosys April 2011 futures were at a premium of 6.50 points at 2928.75 compared with spot closing of 2922.25. The number of contracts traded was 19,210.
SBI's May 2011 futures were at a premium of 24.00 points at 2872.35 compared with spot closing of 2848.35. The number of contracts traded was 18,164.
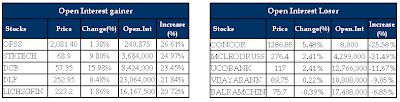
Open Interest Gainer & Looser

Nifty Option Open Inetrest
Nifty Option Open Interest Distribution
Nifty May 5800 call added 7.09 lakh shares in OI, up 51.11% and 5900 call added 6.62 lakh shares in OI, up 37.49%. On the put side nifty May 5700 put added 5.15 lakh shares in OI, up 7.18% and 5600 put added 6.85 lakh in OI, up 21.54%. The put-call ratio of stock option increased from 0.37 to 0.42 while put-call ratio of index option decreased from 0.83 to 0.79. On the whole the put call ratio was at 0.78.

Related post about Derivative Strategy

To more about Future Level Report
Margin Report By Mansukkh

Derivative Strategy On Future And Options Daily Report By Mansukh 15th-April-2011

Derivative Commodity
F & O HIGHLIGHTS
Nifty April 2011 futures closed at 5,798.00, at a premium of 12.30 over spot closing of 5,785.70, while Nifty May 2011 futures were at 5,816.00 at a premium of 30.30 points over spot closing. The near month April 2011 derivatives contract expires on Thursday, April 28, 2011. Nifty April futures saw an addition of 10.22% or 2.60 million (mn) units, taking the total outstanding open interest (OI) to 28.04 mn units.
From the most active underlying, SBI's April 2011 futures closed at a discount of 3.40 points at 2779.25 compared with spot closing of 2782.65. The number of contracts traded was 14,880.
ICICI Bank April 2011 futures were at a premium of 3.70 points at 1101.70 compared with spot closing of 1098.00. The number of contracts traded was 13,462.
Tata Motors April 2011 futures were at a discount of 3.50 points at 1213.50 compared with spot closing of 1217.00. The number of contracts traded was 11,935.
Infosys April 2011 futures were at a premium of 10.80 points at 3247.65 compared with spot closing of 3236.85. The number of contracts traded was 8,359.
Derivative Research Report

Read more about Derivative Research Report By Mansukh
Related  Post Derivative Trading

Equity Research Weekly Market Outlook Report By Mansukh 26-March-2011

Weekly Market Outlook
SNAPSHOT
Despite starting the week with a lackadaisical performance and ending below the crucial support levels of 5,400 and 18,000, the benchmarks convalesced on Tuesday and carried forward the strong rally for rest of the of the week as they vivaciously conquered a lot of psychological levels on their way up. The consolidation in crude prices around $105 levels despite escalating turbulences in the Middle East nations was also seen as an opportunity by the local investors who resorted to broad based buying as tabling of the banking sector amendment bill and the Constitution Amendment Bill in parliament buttressed the chances of a rebound for the domestic indices. Moreover, bourses rallied over two percentage points on the last trading day of the week to finish the action-packed week on an exciting note. The spurt on the last trading day in benchmarks was not only due to sanguine leads from the global market but also on encouraging local cues like the overall growth  in the farm sector being pegged at 5.4% along with finance minister's avowal of 9% growth in the next fiscal in the upper house of Parliament stoking investor sentiments.  

Boisterous Indian stock markets witnessed an awe-inspiring week of trade as it seemed like the bullishness of the recent past has come to the fore. The frontline indices accumulated over a gargantuan five percentage points for the week taking the benchmarks to around two month high levels as optimistic global cues coupled with encouraging local developments fortified investors' mood. The Bombay Stock Exchange (BSE) Sensex surged 936.83 points or 5.24% to 18,815.64 during the week ended March 25, 2011.The BSE Mid-cap index gained 3.25% to 6,721.56 and the Small-cap index advanced 2.61% to 8,001.63. All the sectoral indices on the BSE were in the positive terrain; Realty was up 184.64 points or 8.99% to 2,237.87, Bankex up by 741.78 points or 6.09% to 12926.07, IT up 344.65 points or 5.74% to 6,344.62, TECk up by 198.55 points or 5.62% to 3729.29 and Capital Goods (CG) up by 646.72 points or 5.23% to 12,373.27 were the major gainer. The S&P CNX Nifty zoomed 280.55 points or 5.22% to 5,654.25. On the National Stock Exchange (NSE), Bank Nifty surged 6.27% to 11,387.30, CNX IT soared 5.77% to 6,930.65, CNX Nifty Junior advanced 3.08% to 10,943.10 and CNX mid- cap gained 3.05% to 7,824.15.

WEEK AHEAD
Amidst rising crude oil prices would continue to be threat for the equity markets in the coming week which is characterized by the volatility of  the expiry of F&O series for the month of March, Investor's in the coming week will be eagerly eyeing the core sector growth data, as measured
by the index of six key infrastructure industries, having a combined weight of 26.7% in the Index of Industrial Production (IIP) and also the HSBC India Manufacturing PMI data for the month of March. Further, investor's will keep a close watch on telecom stocks as recommendations on the proposed new policies for telecom infrastructure and manufacturing will be coming in the next week. On the global front, investor's will be eyeing lots of major economic data from the US, starting with Existing Home Sales data on March 21,2011, New Home Sales data, Durable Goods Orders and Jobless Claims data and finally the Corporate Profits data.  Therefore any closing above 5670-5690 for at least two consecutive days may reap indices towards 5800-5850 where we might see some sort of consolidation. On the flip side 5355 still a major support for the March series. HAPPY TRADING…..

Read  more about Equity Research Report